Retirement is a significant milestone, a time many look forward to with anticipation. Yet, for many approaching this new chapter, the thought of navigating Medicare can feel incredibly overwhelming, especially when trying to avoid coverage delays. We understand this sentiment completely; the rules, deadlines, and choices can seem like a complex maze. At Randy Sinanan Medicare Advisors, our mission is to simplify this process, helping you transition into retirement with confidence in your healthcare coverage, free from unexpected gaps or penalties.
Understanding Your Initial Enrollment Period (IEP)
The most crucial step to avoiding Medicare coverage delays is understanding your Initial Enrollment Period (IEP). This is a seven-month window that begins three months before your 65th birthday, includes your birthday month, and extends three months after it. Missing this window for Medicare Part B (Medical Insurance) can lead to permanent late enrollment penalties, meaning you could pay a higher premium for the rest of your life. Even if you plan to continue working, it's vital to assess your situation during this period to ensure you don't inadvertently create gaps or incur penalties. Taking proactive steps to review your options early can save you significant stress and money down the line.
Coordinating Medicare with Employer Coverage
One of the most common sources of confusion, and potential for delay, arises when individuals are still working past age 65 and have health insurance through their employer. If your employer has fewer than 20 employees, Medicare usually becomes your primary payer at 65, and you generally need to enroll in Part B. However, if your employer has 20 or more employees, their group health plan is typically primary, and you can often delay enrolling in Part B without penalty. Once your employer coverage ends, you’ll qualify for a Special Enrollment Period (SEP) to sign up for Medicare Part B. It’s essential to confirm with your employer’s HR department whether your current plan is considered "creditable" coverage to avoid future penalties and ensure a smooth transition once you decide to retire fully.
Securing Your Full Coverage: Beyond Parts A & B
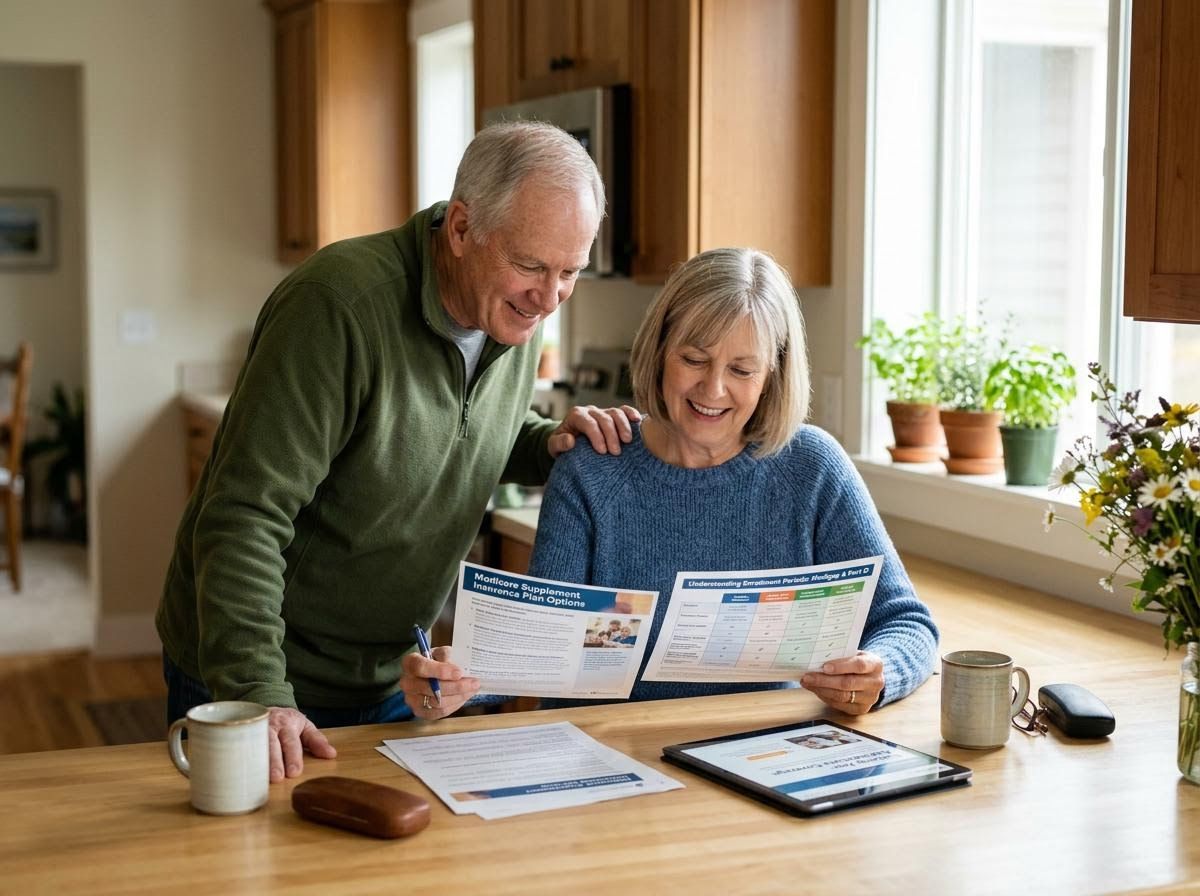
While Part A (Hospital Insurance) and Part B are foundational, they don't cover everything. Many individuals choose to enroll in a Medicare Advantage (Part C) plan or a Medicare Supplement (Medigap) plan along with a Part D (prescription drug) plan. These additional coverages also have specific enrollment periods that often align with your Initial Enrollment Period for Part B. For example, your Medigap open enrollment period starts the month you turn 65 and are enrolled in Part B, lasting for six months. Missing this window can mean you might not be able to buy a Medigap policy, or insurers may charge you more due to health conditions. Planning ahead for these supplemental choices is vital to ensure comprehensive coverage and avoid unexpected out-of-pocket costs in retirement.
Navigating Medicare during retirement doesn't have to be a source of anxiety or confusion. By understanding key enrollment periods, coordinating wisely with existing employer coverage, and planning for your supplemental needs, you can effectively avoid coverage delays and ensure a smooth transition. Don't let the complexities of Medicare keep you from enjoying your retirement to the fullest. To ensure a seamless transition into retirement with confidence in your healthcare, reach out to Randy Sinanan Medicare Advisors for personalized, easy-to-understand guidance today.